
A big chunk of your membership is aging into a tough math problem: retirement income goes down, but the monthly mortgage payment stays the same and property taxes, insurance, and healthcare costs keep climbing. That’s why we sit down with Chris Mayer, CEO of Longbridge Financial, to talk about the product many credit unions still avoid, reverse mortgages, and why the avoidance may be costing members real options and costing credit unions real relationships.
We use HMDA data as the starting point and then get specific about what it’s signaling. Chris shares why older borrowers are frequently denied under standard underwriting, especially when debt-to-income ratios are high, and the borrower is living on a fixed income. We talk through how an FHA-insured HECM reverse mortgage and newer proprietary reverse mortgage products can create a different outcome: access home equity with no required monthly principal and interest payments, designed to support aging in place.
We also tackle the two biggest blockers we hear from credit unions: the stigma around the term “reverse mortgage” and the fear of losing the member relationship if the loan is originated or serviced elsewhere. Chris explains how the right partner can respect the existing relationship, and we outline a practical first step any credit union can take immediately: review your recent denials and incomplete applications for members over 62 to see who could have qualified with a reverse option.
If you care about financial wellness, member retention, and serving members for life, this one is for you. Subscribe, share this with a teammate, and leave a review with your biggest question about reverse mortgages so we can keep the conversation going.
Sponsored by Polygon Research

Newsletter Signup
Stay up to date on all things happening over at ACUMA and sign up for our newsletter!
Guests
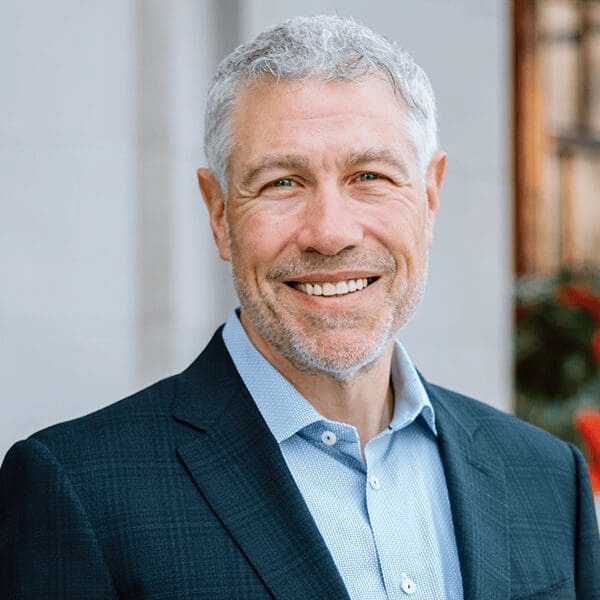
Chris Mayer
Related Podcasts
September 16, 2026
Reverse Mortgages And The Credit Union Blind Spot
August 19, 2026
Turning HMDA Data Into Mortgage Market Advantage

June 25, 2025